The question
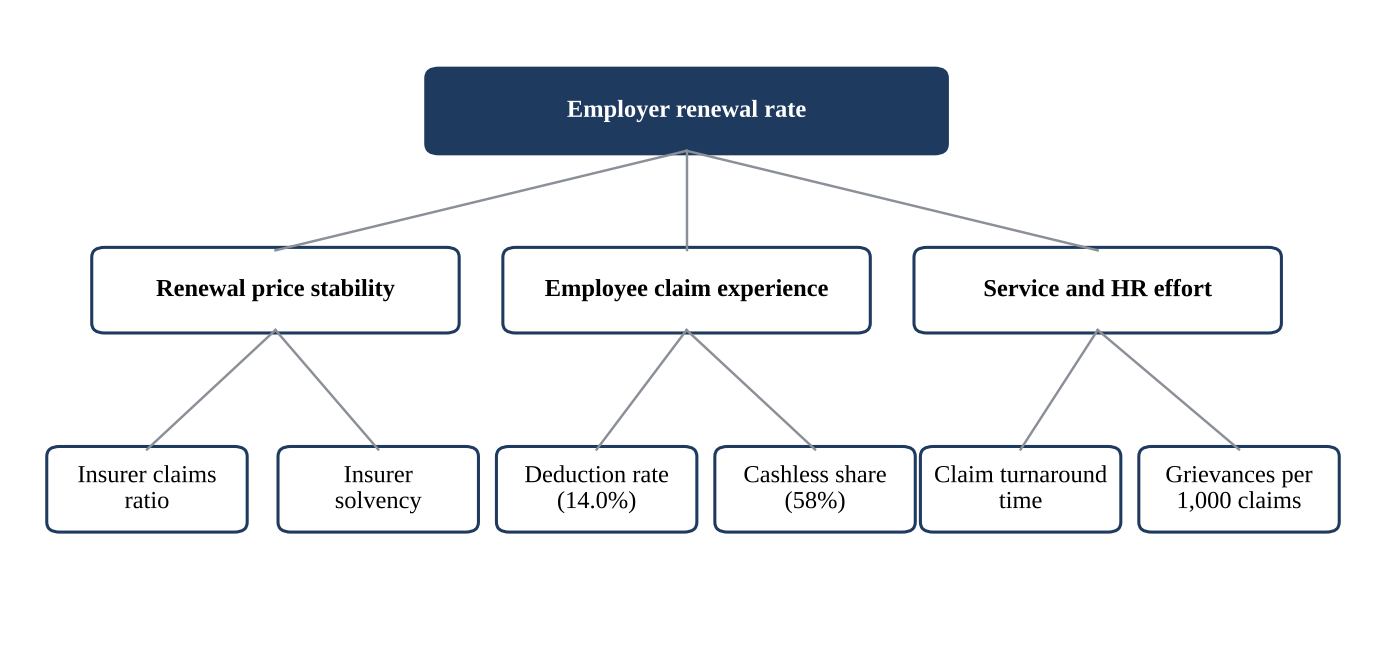
A group-health platform places its clients' risk with insurers. Renewal depends on two things it does not control directly: how insurers price at renewal, and how employees experience claims. Which insurers should it build on, and where should its product team intervene?
Big, growing and thin-margin
₹61,435 crgroup health premium, up 10.4% in 2024-25
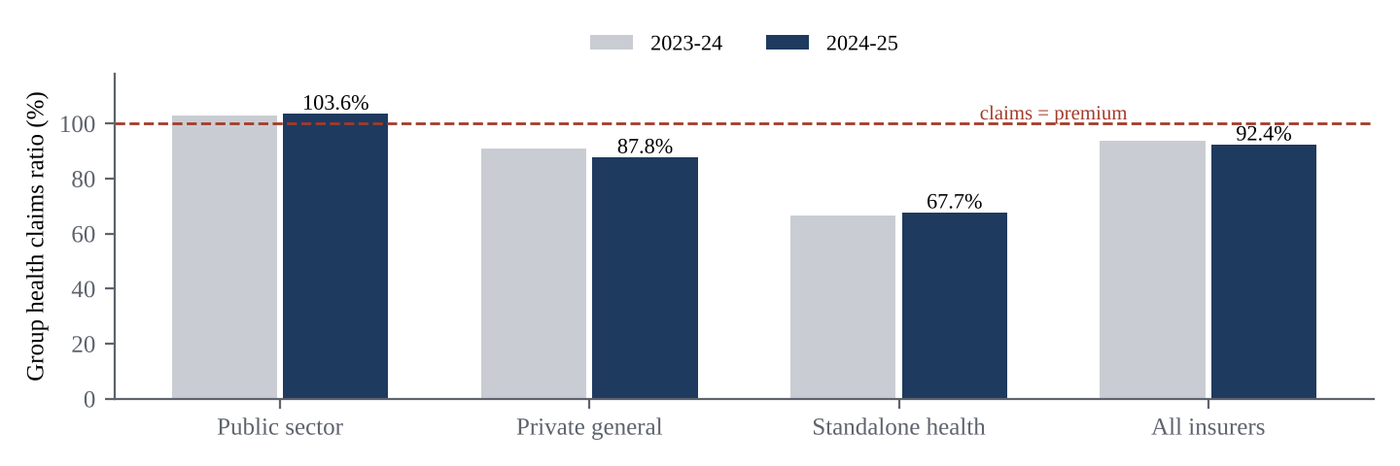
92.4%of group premium paid out as claims
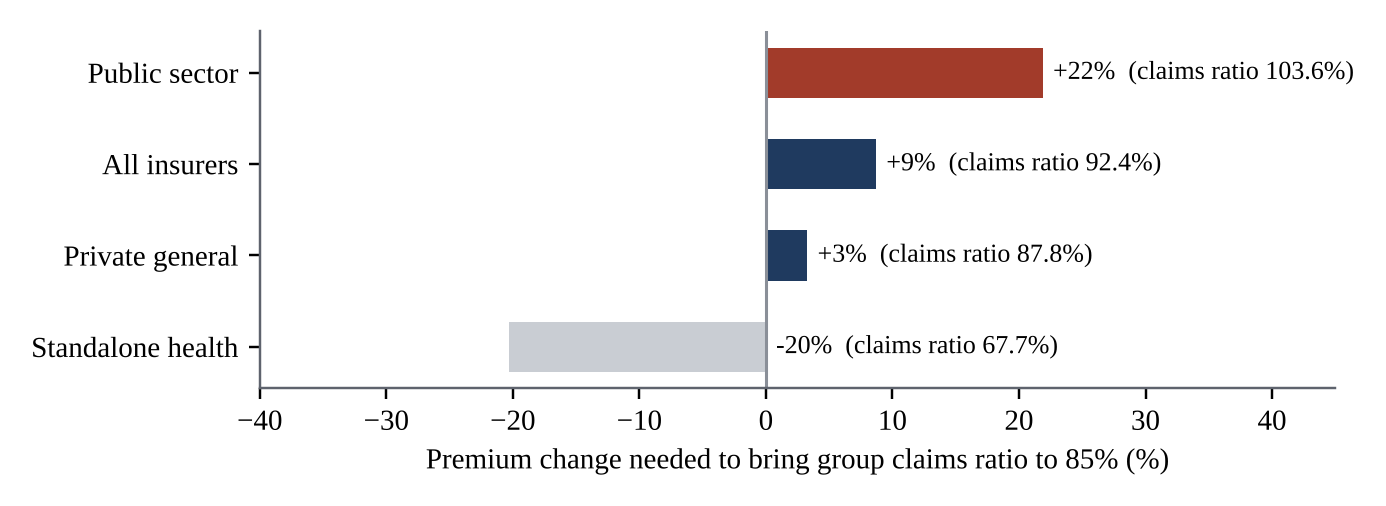
103.6%group claims ratio at public-sector insurers
Partner strategy
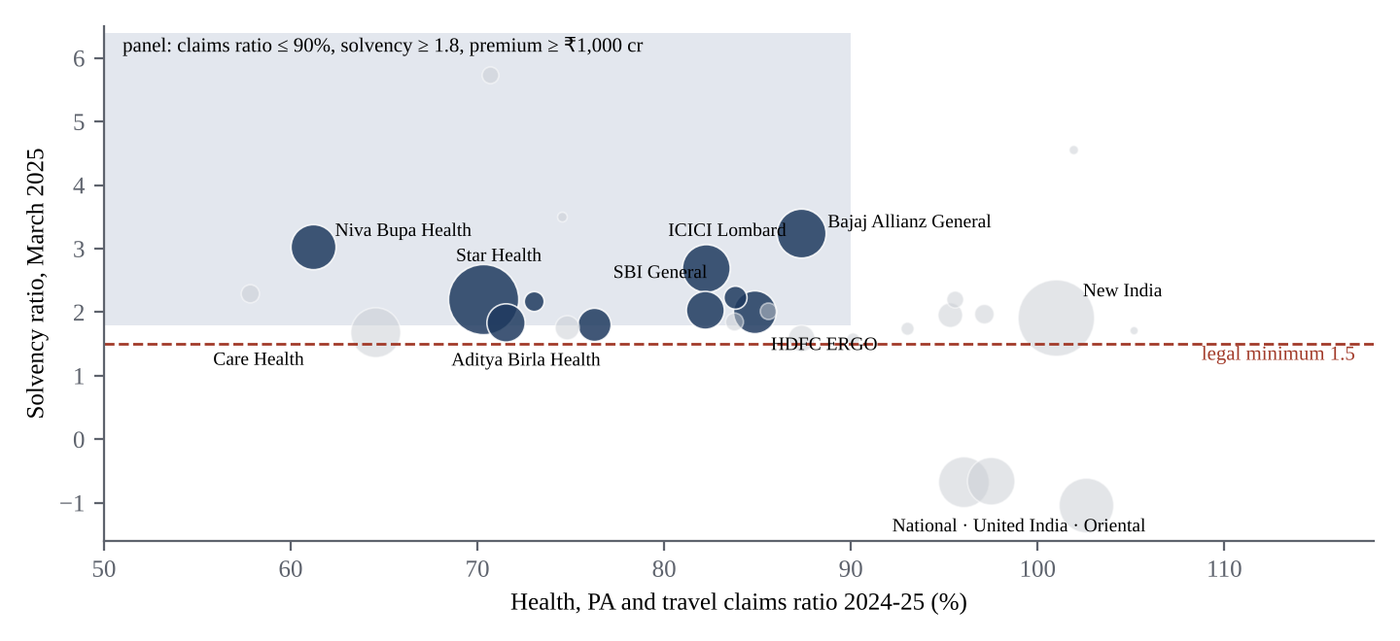
The panel is robust: loosening the claims-ratio threshold to 95% adds no one, and solvency is the threshold that actually moves the list.
Where the claim journey leaks
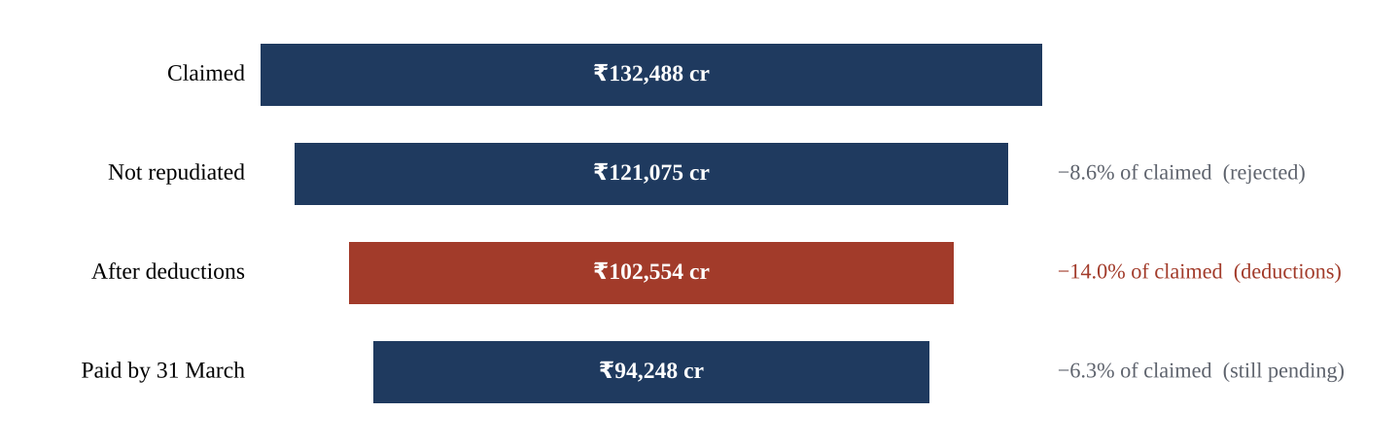
Count-based reporting says 87.5% of claims were paid and hides deductions completely. Cashless covers 58% of paid claims, and the regulator's 2024 rules (pre-authorisation within one hour, discharge within three) give a platform a lever to push it further.
Recommendations
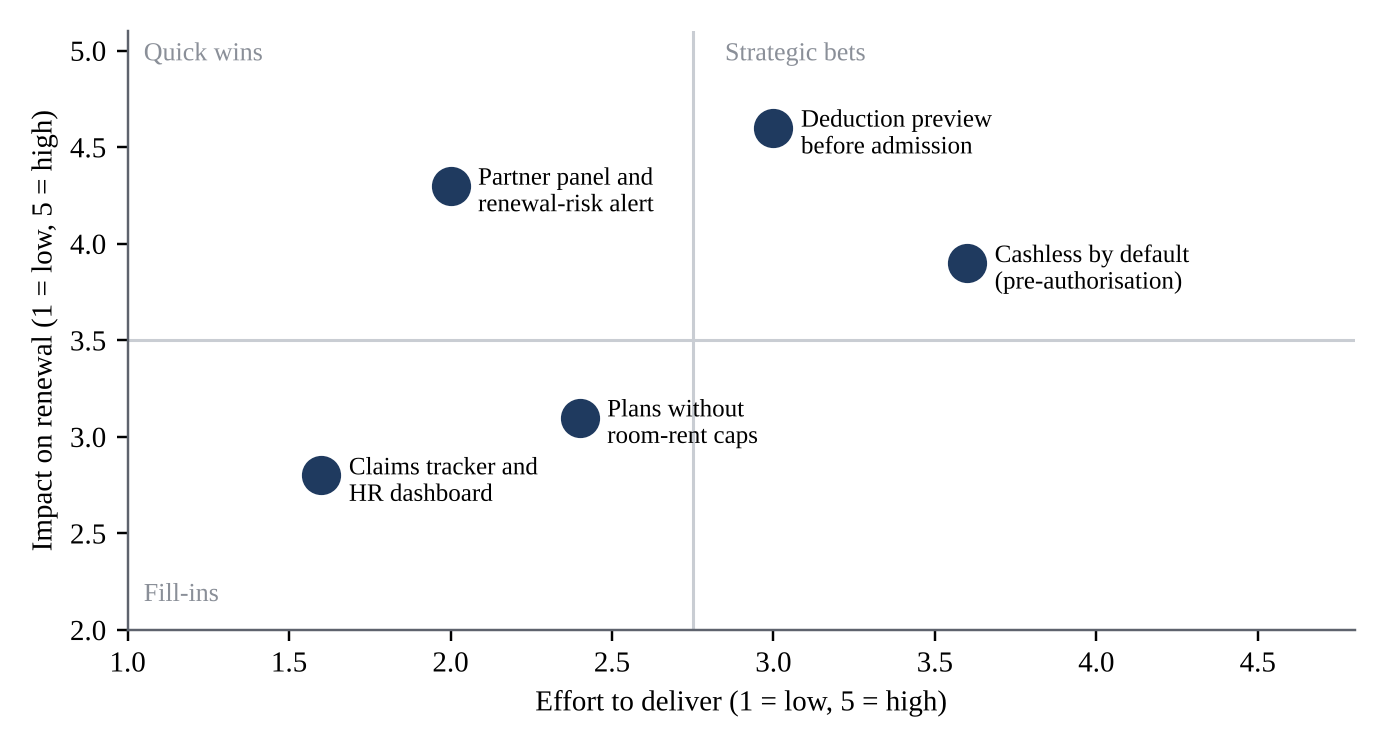
- Build placements on the ten-insurer panel and present it as evidence-based insurer selection.
- Flag at-risk renewals 90 days ahead for clients with insurers above a 100% claims ratio or below the solvency minimum.
- Make deductions the north-star claims metric and show employees their likely deduction before admission.
- Push cashless by default and publish turnaround against the one- and three-hour rules.
All figures
Select a figure to enlarge it.