← All work Product · Transport for London open data

Santander Cycles: getting more from every e-bike

Data 9,048,212 hires, Apr 2025 – Mar 2026Method Diff-in-diff, mix-adjusted benchmark, unit economicsTools Python, pandas, SciPy
TL;DR

Adding 12% more e-bikes in August 2025 added little demand: each new e-bike earns about a third of an existing one. Riders choose e-bikes for long trips, and park and visitor stations run well below the e-bike share their trips predict, which points to price, not supply. Re-deploy before buying, test a casual-rider offer, and decide both with a controlled station test.

Open the full report (PDF, 11 pages) ↗Executive summary, findings, options, test plan and dashboard specification

The question

E-bikes cost far more to buy, charge and maintain than classic bikes. When Santander Cycles added about 230 e-bikes in August 2025, did the extra fleet pay for itself, and where should the next pound of fleet investment go?
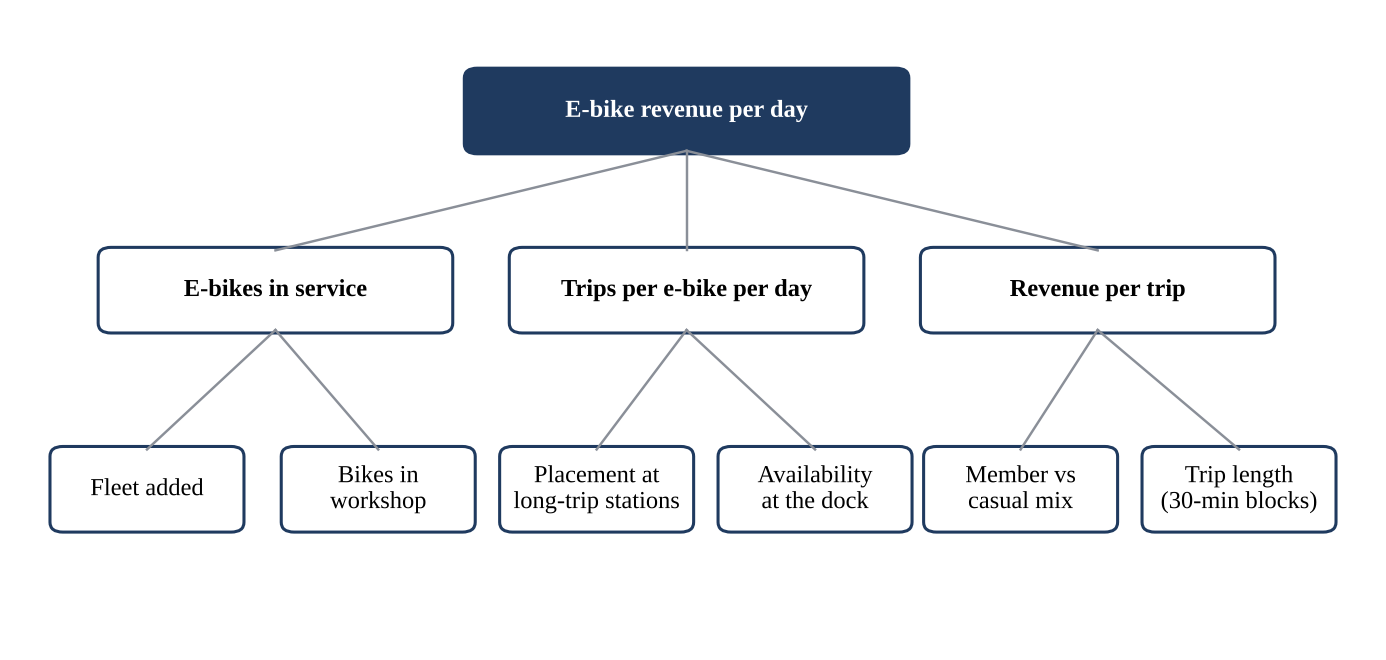
The KPI tree behind the analysisThe KPI tree behind the analysis
E-bike revenue per day = e-bikes in service × trips per e-bike × revenue per trip. The rollout moved the first branch; placement and pricing sit on the other two.

The rollout added fleet, not demand

+12.2%e-bikes in use, June–July to September–October 2025
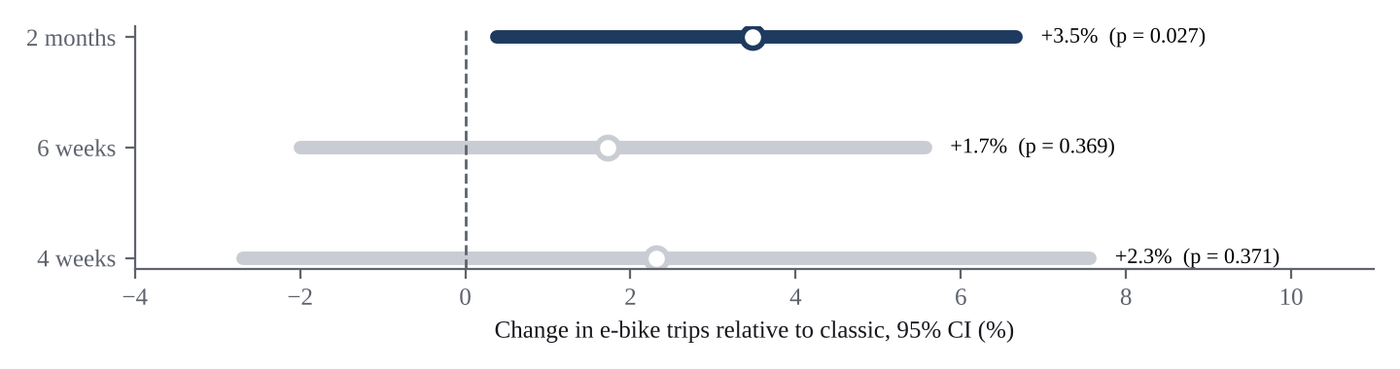
+3.5%e-bike hires relative to classic, two-month windows (95% CI +0.4% to +6.7%)
2.7 → 2.3trips per e-bike per day after the rollout
Only the two-month window is significantOnly the two-month window is significant
Change in e-bike hires relative to classic after the rollout, by comparison window, with 95% confidence intervals.

Classic bikes are the control: weather and events move both, extra supply only moves e-bikes. Counting days rather than trips is what keeps the readout honest: a trip-level test would have called a clear win.

Unit economics of the marginal e-bike
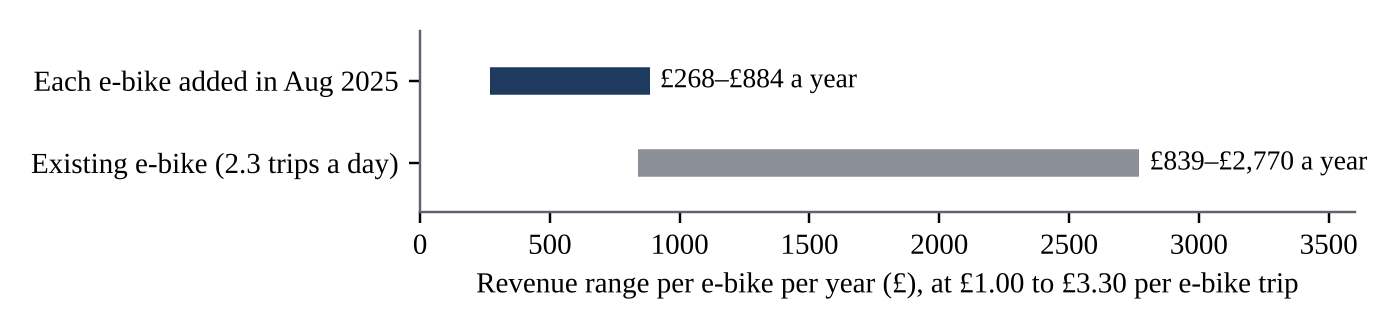
Each new e-bike earns about a third of an existing oneEach new e-bike earns about a third of an existing one
Revenue range per e-bike per year, at £1.00 (member) to £3.30 (casual rider) per e-bike trip.

About 170 extra e-bike hires a day across 233 new bikes is roughly £270 to £880 per new e-bike a year, against £840 to £2,770 for an existing one. Fleet decisions should be judged on marginal, not average, utilisation.

Trip length, not neighbourhood, drives e-bike choice
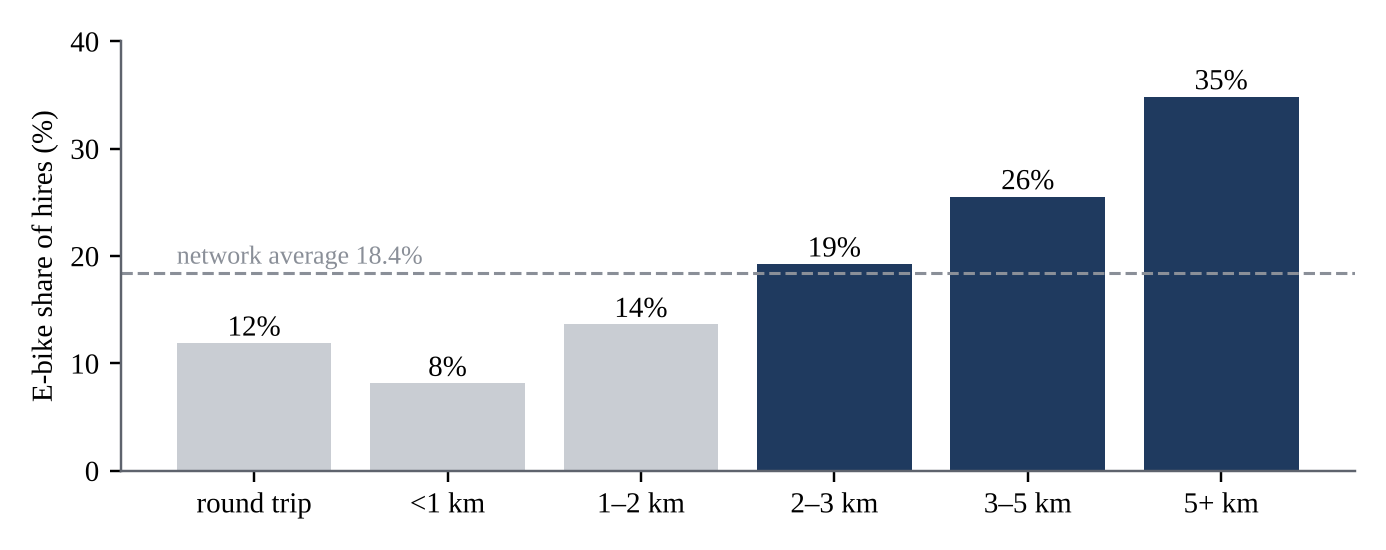
E-bike share climbs with every kilometreE-bike share climbs with every kilometre
E-bike share of hires by straight-line trip length: 8% under 1 km, 35% over 5 km.

E-bike share peaks at 24% to 26% between 03:00 and 06:00 on weekdays and is lowest at midday (16%). It barely changes with distance from central London (17% to 19%).

Which stations are under-served
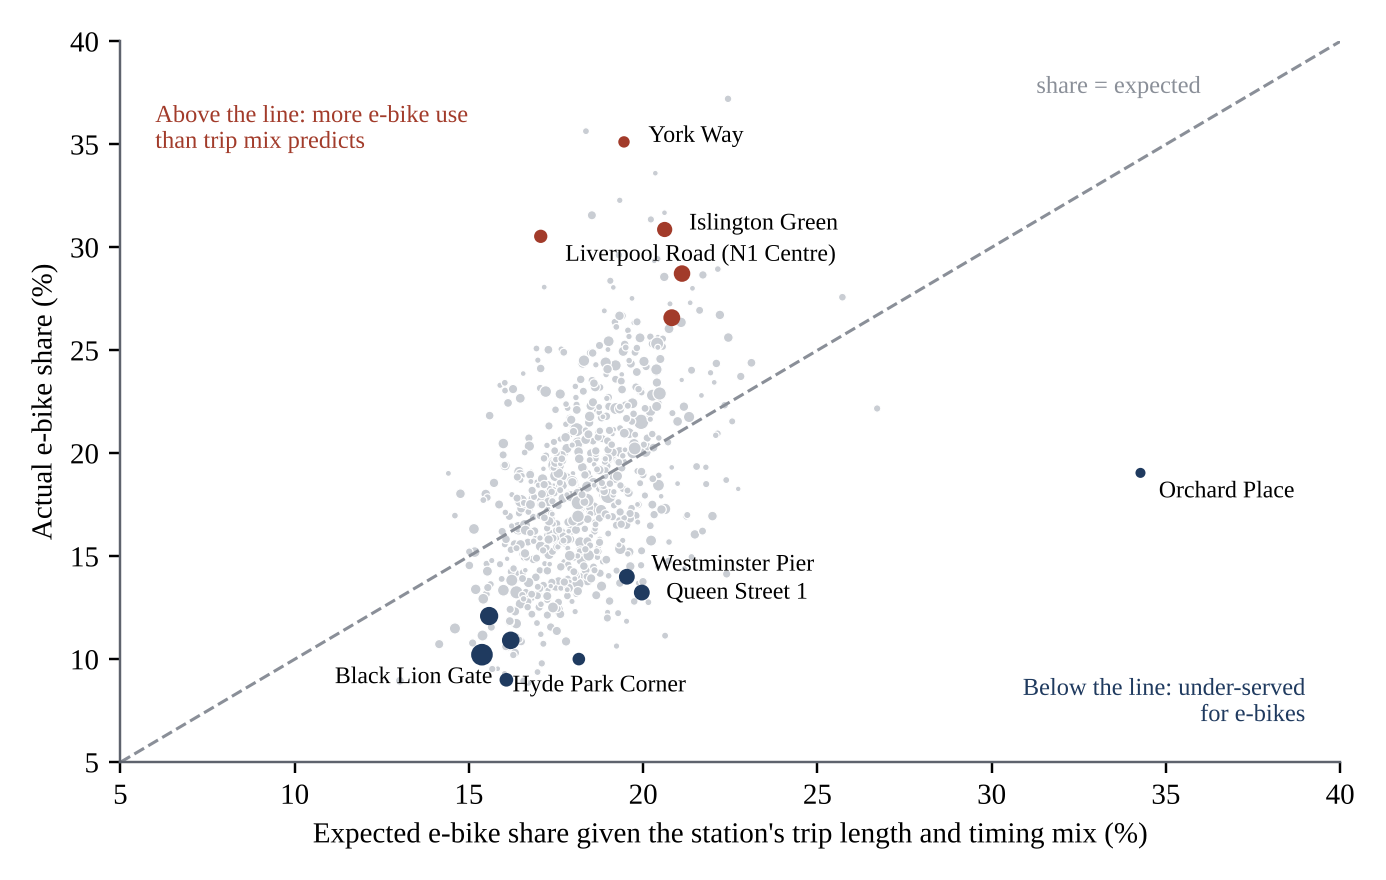
Park and visitor stations run below what their trips predictPark and visitor stations run below what their trips predict
Actual versus mix-adjusted expected e-bike share for 699 stations. Expected share uses the network average for the same trip length, weekday or weekend, and hour.

Hyde Park Corner, Kensington Gardens, South Kensington and Westminster run 5 to 7 points below their expected share; commuter stations at Angel and King's Cross run up to 15 points above. Casual riders pay twice the classic price for an e-bike, while members pay £1 extra per hour, so the gap looks like a price barrier rather than missing bikes.

Recommendations

  • Re-deploy before you buy: move e-bikes towards the 50 stations that start the most long trips; no new purchases until the August batch reaches average utilisation.
  • Pilot a casual e-bike offer at park and visitor stations, measured on net revenue rather than hires.
  • Test, don't roll out: 25 treated and 25 control stations over eight weeks can detect a lift of about 10% to 12%, with classic hires and van time as guardrails.
  • Report marginal utilisation on a shared dashboard for operations, pricing and finance.

All figures

Select a figure to enlarge it.

Check it yourself